The 2026 Construction Supply 150 Shows Why That Matters to Dealers
A new industry benchmark landed in our inbox this spring: the 2026 Construction Supply 150 from Webb Analytics, an annual ranking of North America’s largest building material dealers. We read the full report. It contains no data on ethnicity, language, or the demographics of dealer customers — and that gap is exactly what makes it useful to read alongside federal labor data.
Put the two together and a clear picture emerges: building products is a flat, service-differentiated, labor-constrained market, and the people doing the work on job sites are increasingly Hispanic. That combination has real implications for how dealers, manufacturers and building-products brands spend marketing dollars.
What the 2026 Construction Supply 150 actually says
According to the 2026 Construction Supply 150, the 150 largest construction supply companies took in $424.25 billion in 2025 — a gain of just 1.4% over 2024, which the report attributes largely to inflation. Branch counts rose 10% to 25,097, but mostly through acquisition, not organic demand that can represent the Construction’s Workforce Is One-Third Hispanic. .
Several findings from the report stand out for anyone responsible for demand generation:
- Service, not stock, is the battleground. Installed sales brought $7.69 billion to the 86 CS150 members that offer them — 11% of those companies’ revenue — while The Home Depot and Lowe’s collected $8.2 billion managing mainly third-party installations.
- The big boxes dominate paid media. The report cites $1.3 billion in 2025 advertising spend at The Home Depot and $978 million at Lowe’s. Independent dealers are not going to outbid that.
- Relationships are being systematized. Customer relationship management software is now in place at 46% of survey respondents, up from 27% in 2022, with another 22% planning to buy it.
- People are the constraint. Average payroll costs rose 7.2% in 2025 (n=101). Truck drivers have been the hardest role to fill for four consecutive years, followed by sales reps and yard workers.
The report is based on a Webb Analytics survey plus public filings, with revenue disclosed for 144 of the ranked companies. Sample sizes vary by question, and Webb notes them throughout.
Who is actually holding the tape measure
Construction’s Workforce Is One-Third Hispanic.
The CS150 tells you dealers are competing on service and relationships. Federal data tells you who those relationships are with.
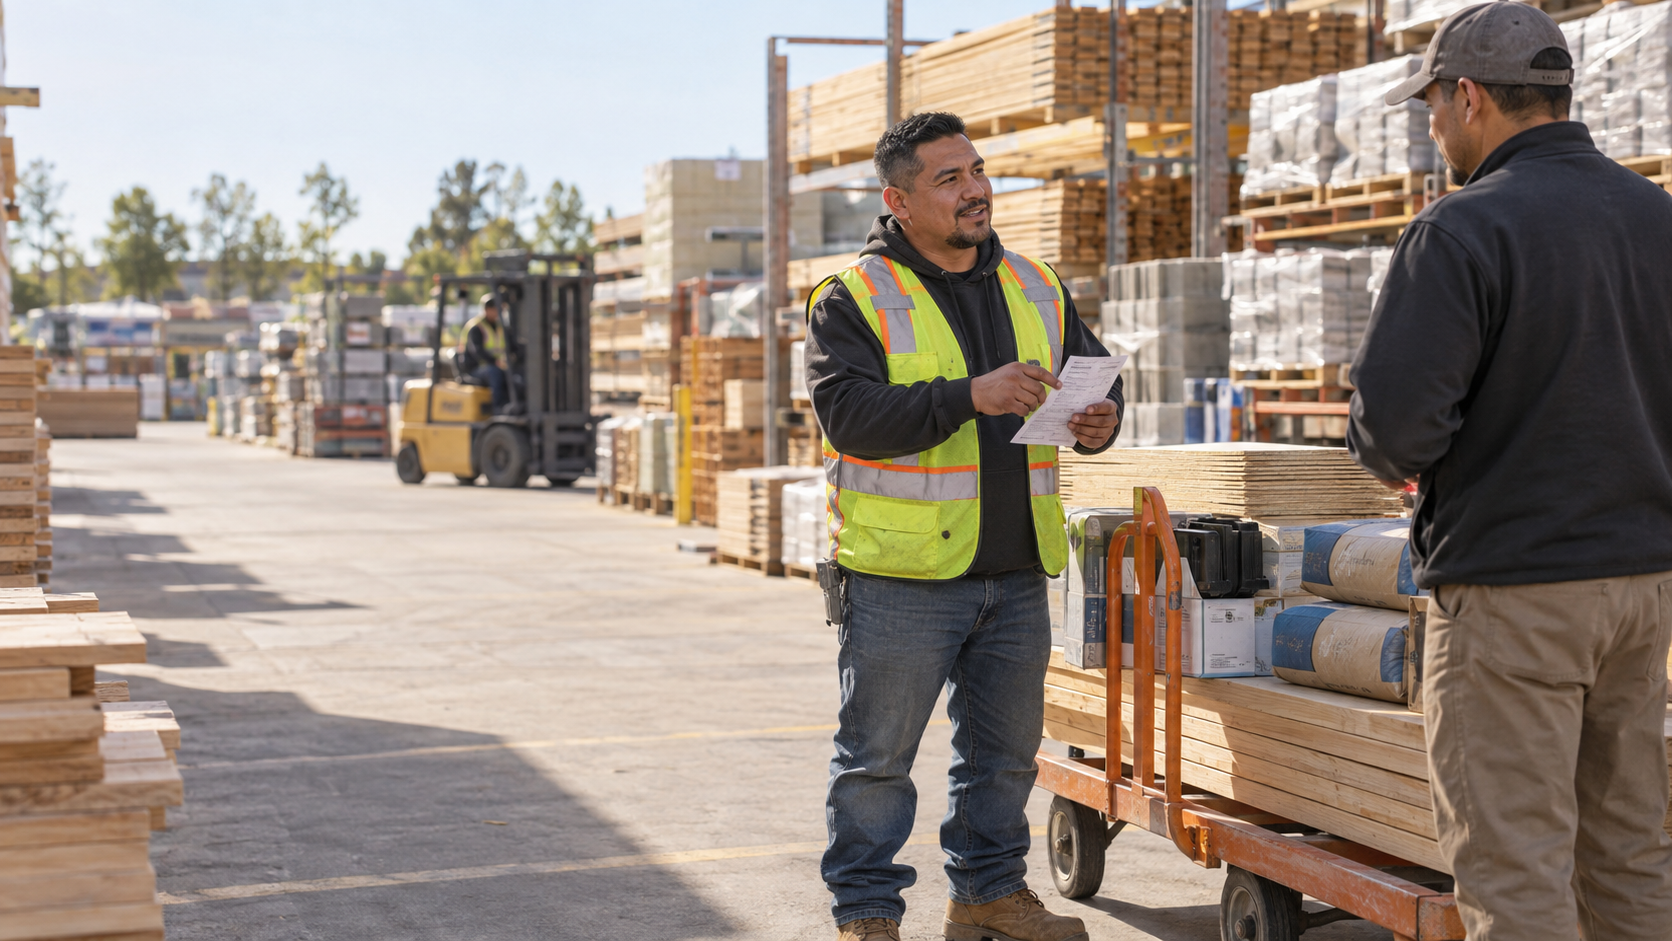
In 2025 annual averages from the Bureau of Labor Statistics’ Current Population Survey, 35.4% of everyone employed in the construction industry was Hispanic or Latino, compared with 20.0% of total U.S. employment. Looking at occupations rather than industry, the concentration is higher still: 41.7% of construction and extraction workers, 55.2% of construction laborers and 43.3% of carpenters are Hispanic. Decision-making roles skew differently — 28.3% of first-line supervisors of construction trades and 20.1% of construction managers.
Two caveats BLS itself flags: the 2025 figures are 11-month averages that exclude October because of the federal shutdown, and industry classifications changed in January 2025, so year-over-year comparisons aren’t strictly valid.
The longer trend is documented by NAHB using the American Community Survey. Hispanic workers grew from 23.6% of the construction labor force in 2010 to 32% in 2023, from 2.5 million to roughly 3.8 million people. The distribution is heavily regional: 61% of Texas construction workers and 64% of New Mexico’s are Hispanic, and Texas, California and Florida together account for 52% of the national Hispanic construction workforce.
Dealers are hiring from the same labor pool
This isn’t only about customers. In the same BLS table, 24.6% of employees at lumber and other construction materials merchant wholesalers were Hispanic, along with 20.0% at building material and supplies dealers. Read next to the CS150’s finding that hiring difficulty and payroll inflation are dealers’ top personnel pressures, recruitment communication looks like part of the same problem set as customer marketing. Construction’s Workforce Is One-Third Hispanic.
Hispanic-owned firms are concentrated in construction
Contractors aren’t just employees — many are the buyers. Census Bureau data from the 2022 Annual Business Survey found 406,086 Hispanic-owned employer firms in 2021, and construction was the single largest sector at 70,571 firms — ahead of accommodation and food services and professional services. In Texas, 14.6% of all employer firms were Hispanic-owned.
These are businesses with payroll, credit lines, delivery windows and purchase orders. They are the customer type the CS150 says dealers are chasing with installed sales, outside sales reps and CRM systems.
Language: bilingual reality, not Spanish-only
Here is where a lot of marketing goes wrong in both directions. Pew Research Center’s analysis of 2024 ACS data found that 71% of U.S. Latinos ages 5 and older — 44.8 million people — speak English proficiently, up from 59% in 2000, while the share speaking Spanish at home declined from 78% to 68%.
Both numbers are large. English proficiency is rising and Spanish use at home remains the majority. A Spanish-only strategy misreads the audience; an English-only strategy misreads it too.
What we recommend — our interpretation, not a research finding
Everything above is documented. The following are 11/11 Media’s recommendations, offered as judgment calls rather than as findings from any of the sources cited:
- Treat bilingual capability as an operational asset, not a translation task. The CS150 shows dealers winning on takeoffs, delivery reliability and installation. Those interactions happen by phone, at the counter and on site. Bilingual counter staff, drivers and reps affect revenue in a way a translated brochure does not.
- Localize before you generalize. Because Hispanic workforce share ranges from 1% in Maine to 64% in New Mexico, national messaging averages are close to useless. Build audience assumptions market by market.
- Segment by role, not by ethnicity. A framing crew lead, a Hispanic-owned remodeling firm’s owner and a purchasing manager have different problems. Language preference is one variable among many, and it does not predict what someone buys.
- Compete where money isn’t the deciding factor. You will not outspend $1.3 billion. Local search, Spanish- and English-language video that shows real crews and real products, WhatsApp-era responsiveness, and trade-community presence are all accessible to a regional dealer.
- Use bilingual content for recruiting, too. If hiring is the binding constraint the CS150 describes, careers pages, driver recruitment and safety onboarding deserve the same language investment as sales material.
- Avoid cultural shorthand. A 68-million-person population is not a segment with one taste, one country of origin or one media habit. Specificity beats symbolism. Construction’s Workforce Is One-Third Hispanic.
What this evidence does not tell you
We could not find credible data on how many building material dealers currently run bilingual marketing, on Spanish-language search demand for building-products categories, or on the Hispanic share of any individual dealer’s customer base. The CS150 does not measure any of those things. Anyone quoting a precise figure on them should be asked for the source. The practical answer is to measure your own accounts, market by market, before setting a budget.
Let’s look at your market
11/11 Media is a Houston-based Hispanic marketing firm working with brands that need to reach bilingual and Spanish-speaking audiences with cultural accuracy rather than translation. Learn how we work, or get in touch and we’ll walk through what the labor and business-ownership data look like in your specific trade area.